
Consumer habits do not usually change all at once. They shift gradually, often in ways that seem insignificant until businesses suddenly realize that their customers are behaving very differently from five or ten years ago. Kavan Choksi has highlighted the growing importance of these shifts because changes in how people spend, save and prioritize their money can eventually reshape entire industries.
For businesses, this creates a difficult problem. Economic data can show whether consumers are spending more or less overall, but it does not always reveal where that spending is moving. A household might reduce expenditure in one area while becoming far more willing to spend in another. The result is that two companies serving the same broad consumer market can experience completely different conditions.
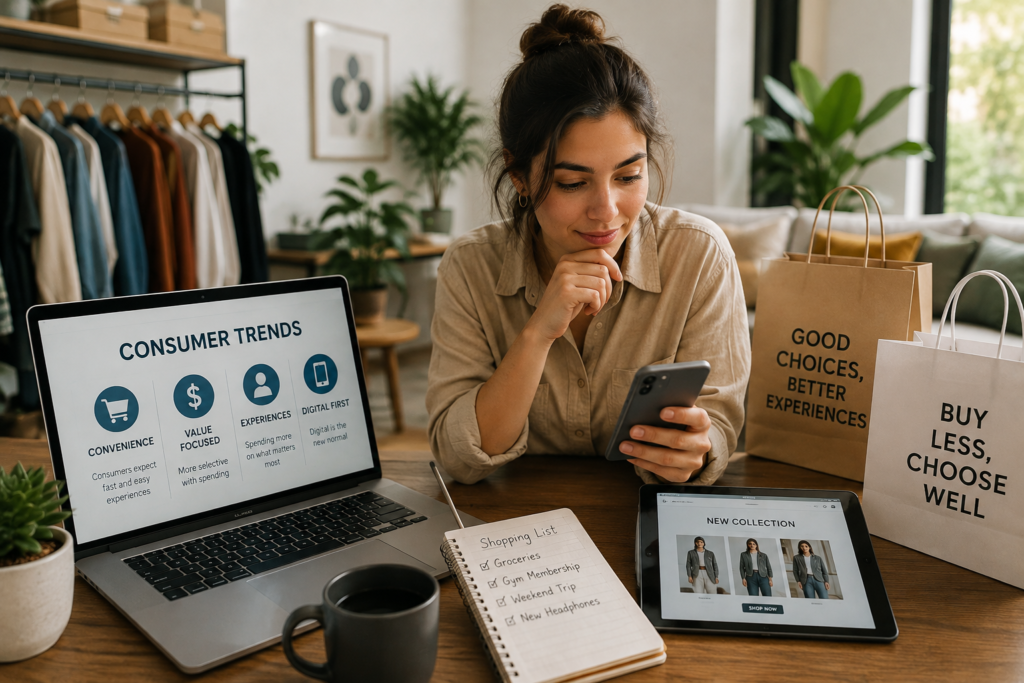
One of the clearest changes has been the growing emphasis on convenience. Consumers have become accustomed to services that remove friction from everyday life, whether that means ordering groceries online, streaming entertainment instantly or managing finances through an app. Once people become used to that level of convenience, expectations tend to spread from one industry to another.
That creates pressure on businesses that previously relied on habit or customer inertia. A company may still offer a perfectly good product, but if buying it feels slow, complicated or inconvenient compared with competing alternatives, consumers may gradually move elsewhere.
Retail has been one of the most obvious examples. The growth of e-commerce did not simply move purchases from stores to websites. It changed what customers expect from the entire shopping process. Faster delivery, easy returns, transparent pricing and personalized recommendations have become increasingly normal. Traditional retailers have therefore had to rethink not just where they sell, but how the whole customer experience works.
The same shift can be seen in financial services. Younger consumers in particular have grown comfortable with banking, investing and making payments through digital platforms. This has encouraged traditional institutions to improve their technology while creating opportunities for newer companies that were built around digital access from the beginning.
However, convenience is only one part of the story.
Consumers have also become more selective about where they spend discretionary income. Periods of higher inflation have forced many households to think more carefully about value, and that does not always mean choosing the cheapest option. In some cases, consumers cut back on routine spending precisely so they can continue paying for products or experiences they value more highly.
This has created an interesting divide between businesses that compete mainly on price and those that can persuade customers they offer something distinctive. A premium travel experience, a favorite technology product or a high-quality service may continue attracting demand even when people are becoming more cautious elsewhere.
That helps explain why consumer weakness is rarely uniform.
Travel provides a useful example. Households may complain about rising living costs while still prioritizing holidays and experiences. This does not necessarily mean financial pressures are insignificant. It may simply indicate that people have reordered their priorities.
The same principle applies to housing. Changes in remote and hybrid working have altered what some buyers and renters value. A shorter commute may matter less than additional space, a home office or access to a different type of neighborhood. Those preferences can influence demand patterns even when the broader property market is being driven by interest rates and affordability.
Demographics add another layer. An aging population creates different spending priorities from a younger one. Healthcare, financial planning and leisure may become more important, while other categories experience slower growth. At the same time, younger consumers can shape markets rapidly when they adopt new technology or spending habits at scale.
Businesses therefore need to think beyond simple questions such as whether consumer spending is rising or falling. The more useful question is often how spending is being redistributed.
This matters to investors as well.
A company operating in a growing industry is not automatically well positioned if it fails to understand how its customers are changing. Conversely, a business in a mature sector can still perform strongly if it adapts effectively to new preferences.
The strongest companies are often those that notice behavioralchanges before they become obvious in headline economic data. They experiment with new distribution channels, rethink pricing or alter their products while competitors are still relying on what worked in the past.
There is also a danger in assuming every change is permanent.
Some consumer habits are shaped by temporary economic conditions. A period of high inflation may encourage people to trade down to cheaper products, but those customers could move back toward premium options once finances improve. Other changes, such as widespread adoption of digital services, may prove far more durable.
Distinguishing between the two is difficult, but important.
It is one reason consumer behavior deserves to be studied alongside traditional economic indicators. Employment, wages and inflation tell us a great deal about how much money households have available. They do not always tell us what people increasingly consider worth spending that money on.
Over time, those decisions accumulate. They determine which stores remain busy, which technologies become mainstream, which services grow and which once-successful business models begin to lose relevance.
Markets often appear to change because of technology, interest rates or competition. Underneath many of those shifts, however, is something much simpler: millions of consumers quietly changing their minds about what they want.